

Get Paid Early: Cash Advance
by StreamFunds, Inc.
4.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.2
- Price
- Free
- Download
- 50.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
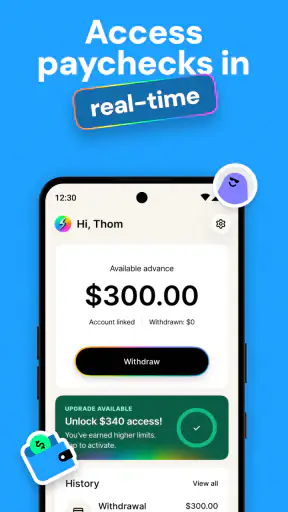
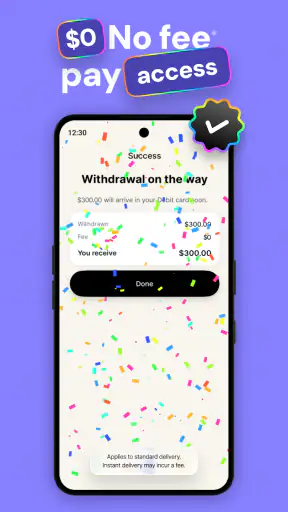
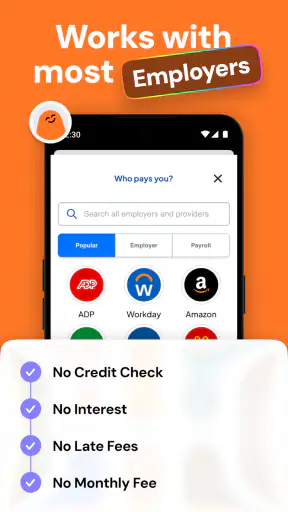
 Analysis by Getfullapps
When money arrives a little later than the bill, the problem is often not long-term debt but timing. Get Paid Early: Cash Advance is a finance app from StreamFunds, Inc. built around that narrow gap: helping eligible users access pay they have already earned before the normal payday. I approached it as a practical cash-flow tool rather than a replacement for budgeting, savings, or regular income.
The first thing I noticed is how clearly the app positions itself. It is free to download, carries an Everyone age rating, and focuses on early access to earned pay rather than presenting itself as a conventional loan product. That distinction matters. If your goal is to handle a short-lived timing problem without applying for a traditional loan, the concept is easy to understand. If you need money for a recurring shortfall, however, the app should be treated as a warning sign in your budget rather than a permanent solution.
From a tight week to money arriving earlier
I find it useful to begin with the exact problem this kind of service is meant to address: a necessary expense arriving before wages do. Before I consider an early-pay request, I’d check whether the bill can be moved or handled another way, then identify the smallest amount that would genuinely help. That decision sets up the next section: how to think about the steps and timing without treating a request as money already received.
The starting condition: a bill before payday
A realistic use case is a worker who has completed shifts, expects normal wages soon, but has a utility bill or grocery need arriving first. In that situation, the useful question is not simply “Can I borrow?” It is “Can I bring forward money I have already earned?” That is the situation this app is designed to address.
I like this framing because it encourages a more careful decision. Before opening the app, I would check the exact amount needed, the date the regular paycheck is expected, and whether the expense can wait. Taking only what solves the immediate problem is safer than treating available access as spending money. The app may make the request feel simple, but the responsibility for the next payday still belongs to the user.
The service is listed as free, with no interest and no hidden fees presented in its store summary. That makes it different from many credit cards, payday loans, and overdraft products, where the cost can be difficult to understand at a glance. Even so, I would still read every screen carefully before confirming a transaction. “Free” should never mean skipping the final review of the amount, timing, and terms shown inside the app.
Beginning the setup without rushing
The opening stage is where I would expect the most important handoff: the app needs enough information to determine whether early-pay access can work for the user. A finance app cannot responsibly move money based on a vague promise of future wages, so the setup should be approached with the same care used for any financial service. I would use accurate personal and employment information, check the destination details twice, and avoid starting the process while distracted.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This is also the point where users should think about privacy. A cash-access service may need financial or employment-related information to evaluate eligibility and arrange delivery. I would review the permission requests and account connections rather than approving everything automatically. The practical trade-off is straightforward: more information may make verification possible, but sharing financial access deserves deliberate attention.
The current release is version 3.0.39, and the stated minimum operating-system requirement is Android 7.0. That makes the app accessible to many older Android phones, which is useful for people who do not replace devices frequently. I would still keep the phone updated where possible, use a screen lock, and avoid signing in over an unsecured public connection. Those habits are especially important when an app deals with income and account details.
Moving from eligibility to a request
Once the initial information is accepted, the key decision is how much to request. My advice is to begin with the smallest amount that covers the specific gap. For example, if a bill is short by a modest amount, requesting extra simply because the option appears available weakens the benefit of using an earned-pay service. The best workflow connects the request to a named expense and a known repayment or payroll timeline.
This is one of the app’s practical strengths: it addresses a defined cash-flow moment instead of asking the user to manage a broad revolving balance. Compared with a credit card, there is less temptation to carry a balance indefinitely if the access is tied to earned pay. Compared with a traditional loan, the process is aimed at a smaller and more immediate need. The trade-off is that it is not a solution for large purchases, long repayment periods, or income that is already unstable.
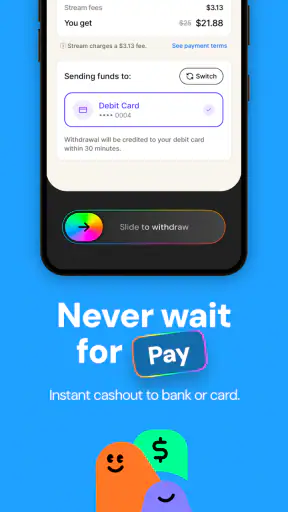
I would pause at the confirmation screen and check three things: the amount being requested, where it is going, and when the normal pay cycle is expected to catch up. This small pause is an important non-obvious safeguard. Speed is the appeal of early-pay apps, but speed also makes accidental selections easier. A few seconds spent reviewing the request can prevent a much longer financial headache.
The handoffs that matter
The app is only one part of the process. Money has to move through several handoffs: from the user’s work and pay information to the service, from the service to the selected destination, and eventually back into the user’s normal income cycle. Each handoff can introduce delay or require an additional check. I would not plan a payment down to the last minute simply because an early-access request has been submitted.
This is where expectations matter. “Early” does not necessarily mean “instant in every situation.” Processing, verification, banking schedules, or an incorrect destination can affect the practical result. I would submit a request before the bill becomes urgent, keep confirmation details, and watch the receiving account rather than assuming the transfer has completed. That workflow is more realistic than treating the app like cash already in hand.
The receiving account is another place where care pays off. Before confirming, I would make sure the destination belongs to me and that the account can accept the transfer. If a household member normally manages bills, I would coordinate with that person rather than sending money somewhere unexpected. A financial app can simplify the request, but it cannot repair a mistake caused by unclear household communication.
What the result looks like in everyday use
In the best-case scenario, the outcome is modest but useful: a worker handles the bill, avoids a missed payment, and reaches the regular payday without taking on interest-bearing debt. That is a good fit for a temporary mismatch between earned income and the date an expense is due. I would describe the app’s value as reducing friction around timing, not increasing income.
The result is also easier to judge when the user records it. I would note the amount accessed, the expense it covered, and how comfortable the following pay period felt. If the next payday is repeatedly smaller than expected because early access has become routine, that is evidence the app is being used to cover a structural budget problem. At that point, a spending review, payment arrangement, emergency fund plan, or income change may be more helpful.
Its audience is fairly specific. It should appeal to someone with earned pay arriving on a predictable schedule who occasionally needs access sooner. It is less suitable for someone who has no reliable upcoming income, needs a large amount, wants to build credit, or is looking for a general-purpose budgeting platform. A credit-building product, bank overdraft arrangement, employer payroll option, or simple savings buffer may be a better choice depending on the actual problem.
Where the flow breaks
The first possible break is eligibility. Not every user will necessarily be able to complete the process in the same way, and an app centered on earned pay depends on information that can be checked. If the employment or income details do not line up, the service may not solve the immediate problem. I would avoid planning an essential payment around access until the request has actually been accepted and the delivery path is clear.
The second break is timing. A user may open the app because a payment is due today, only to discover that the handoff takes longer than expected. This is why I see the app as a planning tool for short gaps, not an emergency guarantee. If a late bill would trigger serious consequences, contacting the provider directly may be the safer first move while the cash-access request is considered separately.
The third break is behavioral. Easy access can encourage repeated advances, especially when the app makes the request feel less serious than a loan application. The absence of interest does not make an advance free of consequences: bringing pay forward can leave less available later. I would set a personal rule, such as using it only for a defined essential expense and not for discretionary shopping. That boundary is more valuable than any single convenience feature.
There is also a comparison issue. Traditional payday loans can be expensive and create a cycle that is difficult to escape, so an earned-pay option may be preferable for a short, clearly understood gap. Credit cards offer broader flexibility and may be better for purchases that need dispute protection or a longer repayment plan, but they can carry interest if the balance is not cleared. Bank overdraft services may be simpler for existing customers, while employer-provided payroll access may fit better when it is already available through the workplace.
How I would use it responsibly
I would start with a written mini-plan: identify the expense, calculate the smallest amount required, confirm the next regular payday, and decide what spending will be reduced afterward. This turns the app from an impulse button into one step in a cash-flow plan. I would also keep a record of the request and check the normal pay statement afterward so I could see whether the expected adjustment occurred.
A second useful habit is separating urgency from importance. A grocery purchase may be essential, while a subscription renewal might be cancellable or postponable. Before requesting access, I would contact the company behind the bill, look for a due-date change, or use an existing buffer if that avoids moving pay forward. The app is most valuable when it prevents a costly short-term consequence, not when it simply makes every purchase easier.
A third tip is to test the workflow before relying on it. I would complete account setup during a calm period, review how the screens work, and understand the destination details before an urgent bill appears. Financial tools are easier to evaluate when there is time to read carefully. This also helps reveal whether the app fits my habits or whether a bank feature or workplace option would be less complicated.
What the public response suggests
The app has passed fifty thousand installs and holds an average rating of 4.2 from around seven hundred ratings, with roughly one hundred sixty-five written reviews. Those figures suggest that many people find the basic idea useful, while the rating also reminds me not to treat every experience as identical. Finance apps are highly dependent on a user’s employer, pay schedule, bank setup, and urgency, so a positive general impression does not guarantee a smooth result for every person.
I would read written feedback for workflow clues rather than focusing only on the average. Comments about verification, transfer timing, account connections, or support are more useful to a prospective user than praise that simply says the app is convenient. That is a good general rule for this category: look for details that match your own situation, especially if you are considering it because a bill is already close to its deadline.
My recommendation after following the full workflow
After looking at the process from the initial cash shortage through the request, handoffs, and eventual payday, I see Get Paid Early: Cash Advance as a focused tool with a sensible use case. Its strongest point is the attempt to address earned income arriving at the wrong time, without presenting the experience as a conventional interest-bearing loan. The free price and straightforward purpose make it worth considering for eligible users who need occasional breathing room.
I would recommend it to a worker with predictable pay, a specific short-term expense, and enough discipline to keep the request small. I would not recommend relying on it for rent every month, covering an income gap that keeps growing, or funding wants that can wait. In those situations, the app may smooth over the symptom while leaving the underlying problem untouched.
StreamFunds, Inc. has made a finance app that is easy to understand at the concept level, but the real value depends on how carefully the user manages the surrounding workflow. Use it as a controlled bridge, not as an extension of your paycheck. If you can name the expense, verify the timing, review the handoffs, and accept the effect on the next pay cycle, it can be a practical addition to your financial toolkit. If those conditions are not true, a slower but more predictable alternative is likely the wiser choice.
Pros
- Fast access to part of your earned wages before payday.
- Simple application process with minimal paperwork required.
- No traditional credit check for most cash advance requests.
- Repayment is typically automatic from your next paycheck.
- Useful for handling short-term, unexpected expenses.
Cons
- Advance limits may be low for new or infrequent users.
- Optional express transfers can involve additional fees.
- Access may depend on employer or payroll provider support.
- Late repayment could affect future advance eligibility.
- Requires sharing sensitive employment and financial information.
FAQs for Get Paid Early: Cash Advance
What is Get Paid Early: Cash Advance?
Get Paid Early: Cash Advance is a financial app designed to help eligible users access part of their expected income before their regular payday. Depending on the available service and your profile, the app may offer cash advances, budgeting tools, or other money-management features. It is not a replacement for a bank account or long-term financial planning, so review the terms carefully before requesting funds.
How does the cash advance process work?
After creating an account, you may need to provide personal information and connect a qualifying bank account or income source so the app can assess eligibility. If approved, you choose an available advance amount and delivery option. The money may arrive quickly, although timing can vary by bank, verification status, weekends, and the selected transfer method. Approval is not guaranteed for every user.
Does Get Paid Early: Cash Advance charge fees or interest?
Costs can vary depending on the advance, transfer speed, membership plan, or other services offered through the app. Some transactions may include optional or mandatory fees, while certain products may have different repayment terms. Before confirming a request, carefully check the total repayment amount, due date, recurring charges, and any disclosures shown in the app. Never assume that an advertised advance is completely free.
What are the eligibility and repayment requirements?
Eligibility may depend on factors such as age, residence, identity verification, a supported bank account, regular income, and account history. The app may also require permission to review transaction or employment information. Repayment is commonly scheduled for a future payday or another stated date, so make sure sufficient funds will be available. Missing repayment can lead to additional fees, account restrictions, or financial stress.
Is Get Paid Early: Cash Advance safe and worth downloading?
The app can be useful when a small, short-term cash gap occurs, particularly if you understand the costs and have a reliable repayment plan. However, users should review its privacy policy, permissions, customer support information, and current terms before sharing financial data. Cash advances can become expensive if used repeatedly, so compare the service with alternatives such as employer pay access, a bank option, or a local credit union.

Get Paid Early: Cash Advance
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@getstreamapp.com, visit http://www.getstreamapp.com, or review their https://www.getstreamapp.com/legal/privacy.










